OUR VERDICT
Financial decisions made with complete information consistently outperform those made under pressure or with incomplete data. Take time to compare at least 3 options before committing.
Upstart wins for borrowers with thin credit files or non-traditional backgrounds. Avant wins for borrowers who want predictable rates and a straightforward application. Upstart is rated 'Excellent' on Trustpilot.
💡 Expert Tip: Check Your Rate Before You Commit
Upstart offers prequalification with a soft credit pull — meaning you can check your rate in minutes without any impact to your credit score. Before applying, review your debt-to-income ratio (DTI): Upstart looks for a DTI below 45–50%. Divide your total monthly debt payments by your gross monthly income to calculate yours. A lower DTI improves your approval odds and typically results in a lower APR.
Side-by-Side Comparison
Upstart Personal Loans
Unique advantage: AI underwriting considers education and employment — good for recent graduates
✓ Pros
- Accepts 580+ credit scores
- AI considers education/employment history
- Good for thin credit files
- Fast funding (1 business day)
- No prepayment penalty
✗ Cons
- Origination fee up to 12%
- Only 3 or 5 year terms
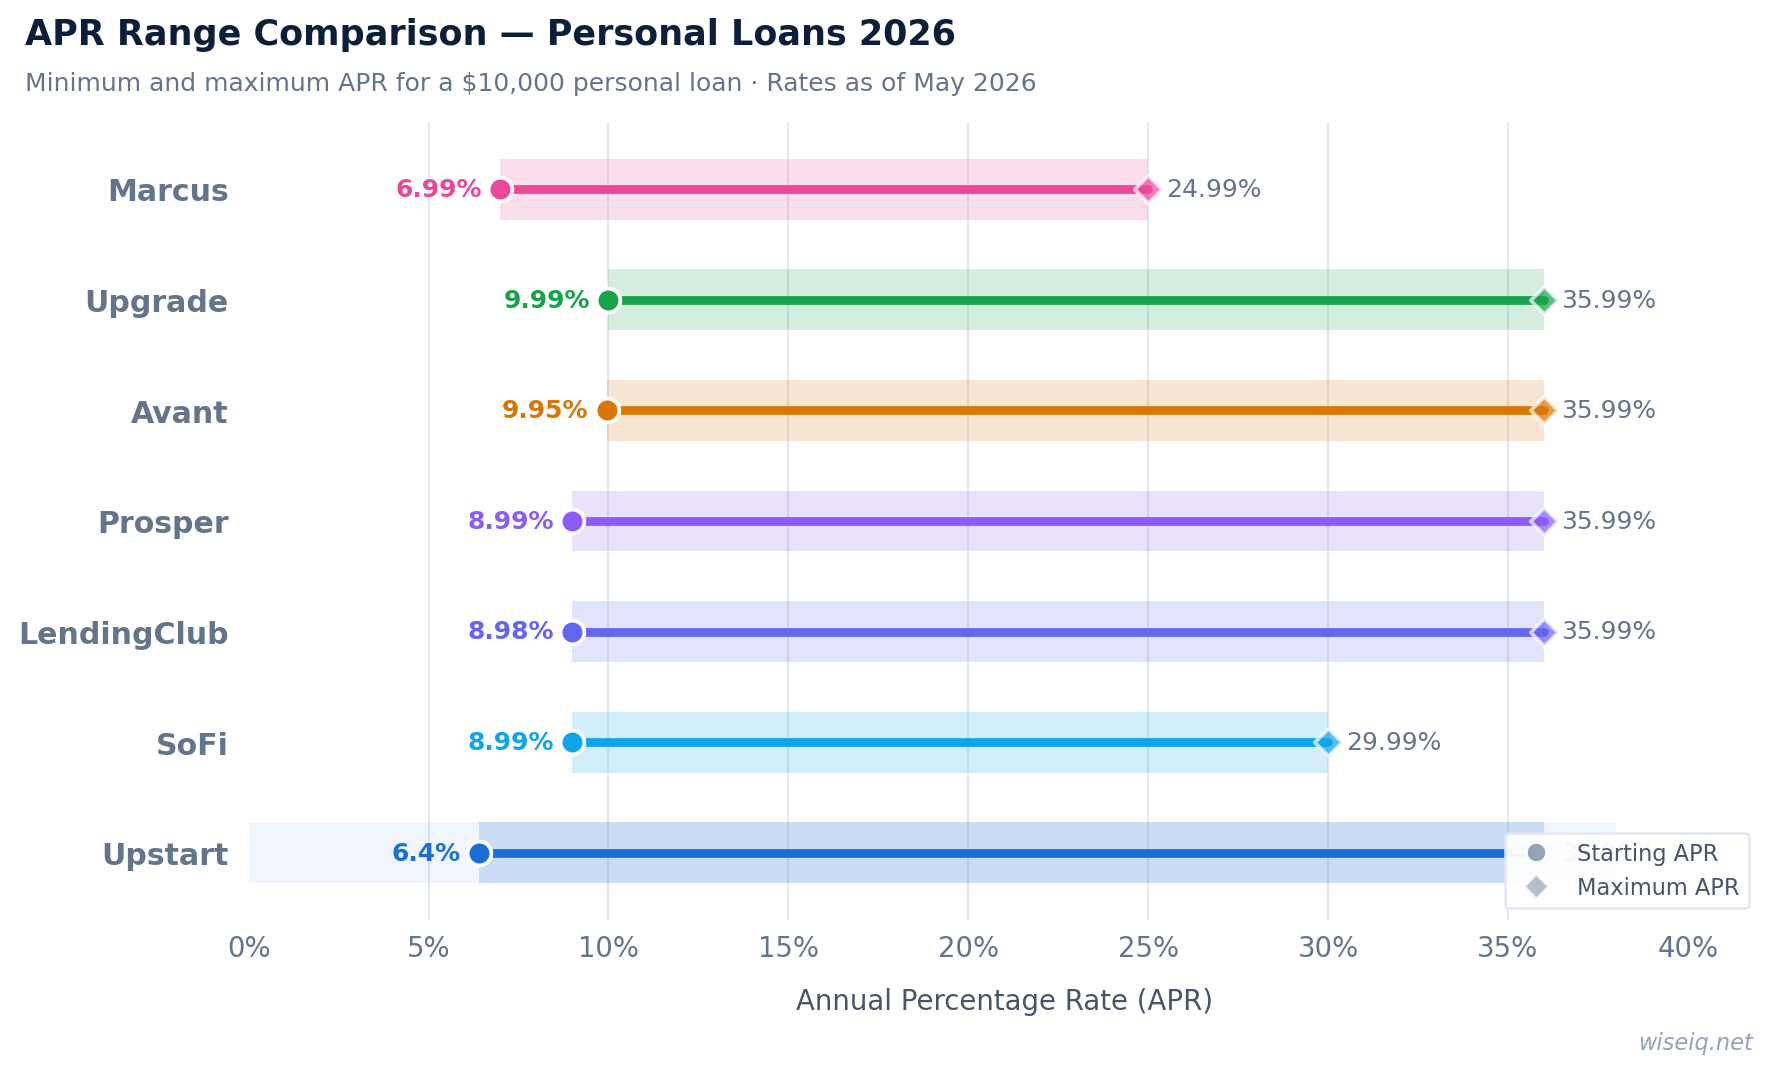
- High maximum APR (35.99%)
- Rates can be high for fair credit
Avant Personal Loans
Unique advantage: Specializes in fair credit borrowers — more predictable approval for 580–669 scores
✓ Pros
- Specializes in fair credit
- Lower origination fee (max 4.75%)
- More flexible terms (2–5 years)
- Predictable approval for 580–669
- Good customer service
✗ Cons
- Higher minimum APR (9.95%)
- Lower maximum loan ($35,000)
- Not available in all states
Getting approved and getting funded are two different steps, and most people who lose the loan lose it in between. Three things that decide it:
- Ask for what your score supports. Under a 660 score, $5,000 to $15,000 gets approved far more often than $25,000 and up. A smaller request usually means a real offer instead of a decline.
- Accept and verify the same day. Offers expire. Have a recent pay stub or bank statement ready to upload, and answer the verification email or call quickly.
- The origination fee comes out of the deposit. It runs 0% to 12%. A $10,000 loan with an 8% fee puts $9,200 in your account, so size the request with the fee in mind.
Detailed Comparison
| Feature |  Upstart Personal Loans |
 Avant Personal Loans |
|---|---|---|
| APR Range | 6.3%–35.99% | 9.95%–35.99% |
| Loan Amount | $1,000–$50,000 | $2,000–$35,000 |
| Loan Terms | 3 or 5 years | 2–5 years |
| Minimum Credit Score | 580+ | 580+ |
| Origination Fee | 0%–12% | Up to 4.75% |
| Funding Speed | 1 business day | 1 business day |
| AI Underwriting | Yes | No |
| Prepayment Penalty | None | None |
| Available States | Most states | Most states (not CO, IA, WV) |
Choose Upstart Personal Loans if:
Upstart is best for borrowers with thin credit files, recent graduates, or those with non-traditional income who may be underserved by traditional underwriting.
Choose Avant Personal Loans if:
Avant is best for borrowers with established fair credit (580–669) who want predictable approval odds and a lower origination fee.
See who actually approves your score range — and the APR to expect.
Who Upstart Is Best For
⚠️ Not a fit if: you need a secured loan, have a bankruptcy in the last 12 months, or need more than $50,000.
What Happens When You Click — 3 Steps
Soft pull only · No impact to your credit score · Takes 2 minutes
Frequently Asked Questions
Is Upstart or Avant better for bad credit?
Both accept 580+ credit scores. Upstart's AI underwriting can be advantageous for borrowers with thin files or non-traditional backgrounds (recent graduates, self-employed). Avant specializes in fair credit and has a lower maximum origination fee (4.75% vs 12%). For most fair-credit borrowers, Avant's lower origination fee makes it the better choice.
What is Upstart's minimum credit score?
Upstart accepts applicants with credit scores as low as 580. However, Upstart's AI model also considers education level, employment history, and area of study, so some applicants with no credit score may also qualify.
Does Avant charge origination fees?
Yes. Avant charges an origination fee of up to 4.75%, which is deducted from your loan proceeds. On a $10,000 loan, you'd receive $9,525 but owe $10,000. Factor this into your total cost calculation when comparing lenders.