Choosing between Upstart and Upgrade comes down to your credit profile, how much you need to borrow, and how quickly you need funds. Both are legitimate online lenders, but they serve different borrower profiles. This guide breaks down every key difference so you can make a confident decision.
Financial decisions made with complete information consistently outperform those made under pressure or with incomplete data. Take time to compare at least 3 options before committing.
Side-by-Side Comparison
| Feature |  Upstart |
 Upgrade |
|---|---|---|
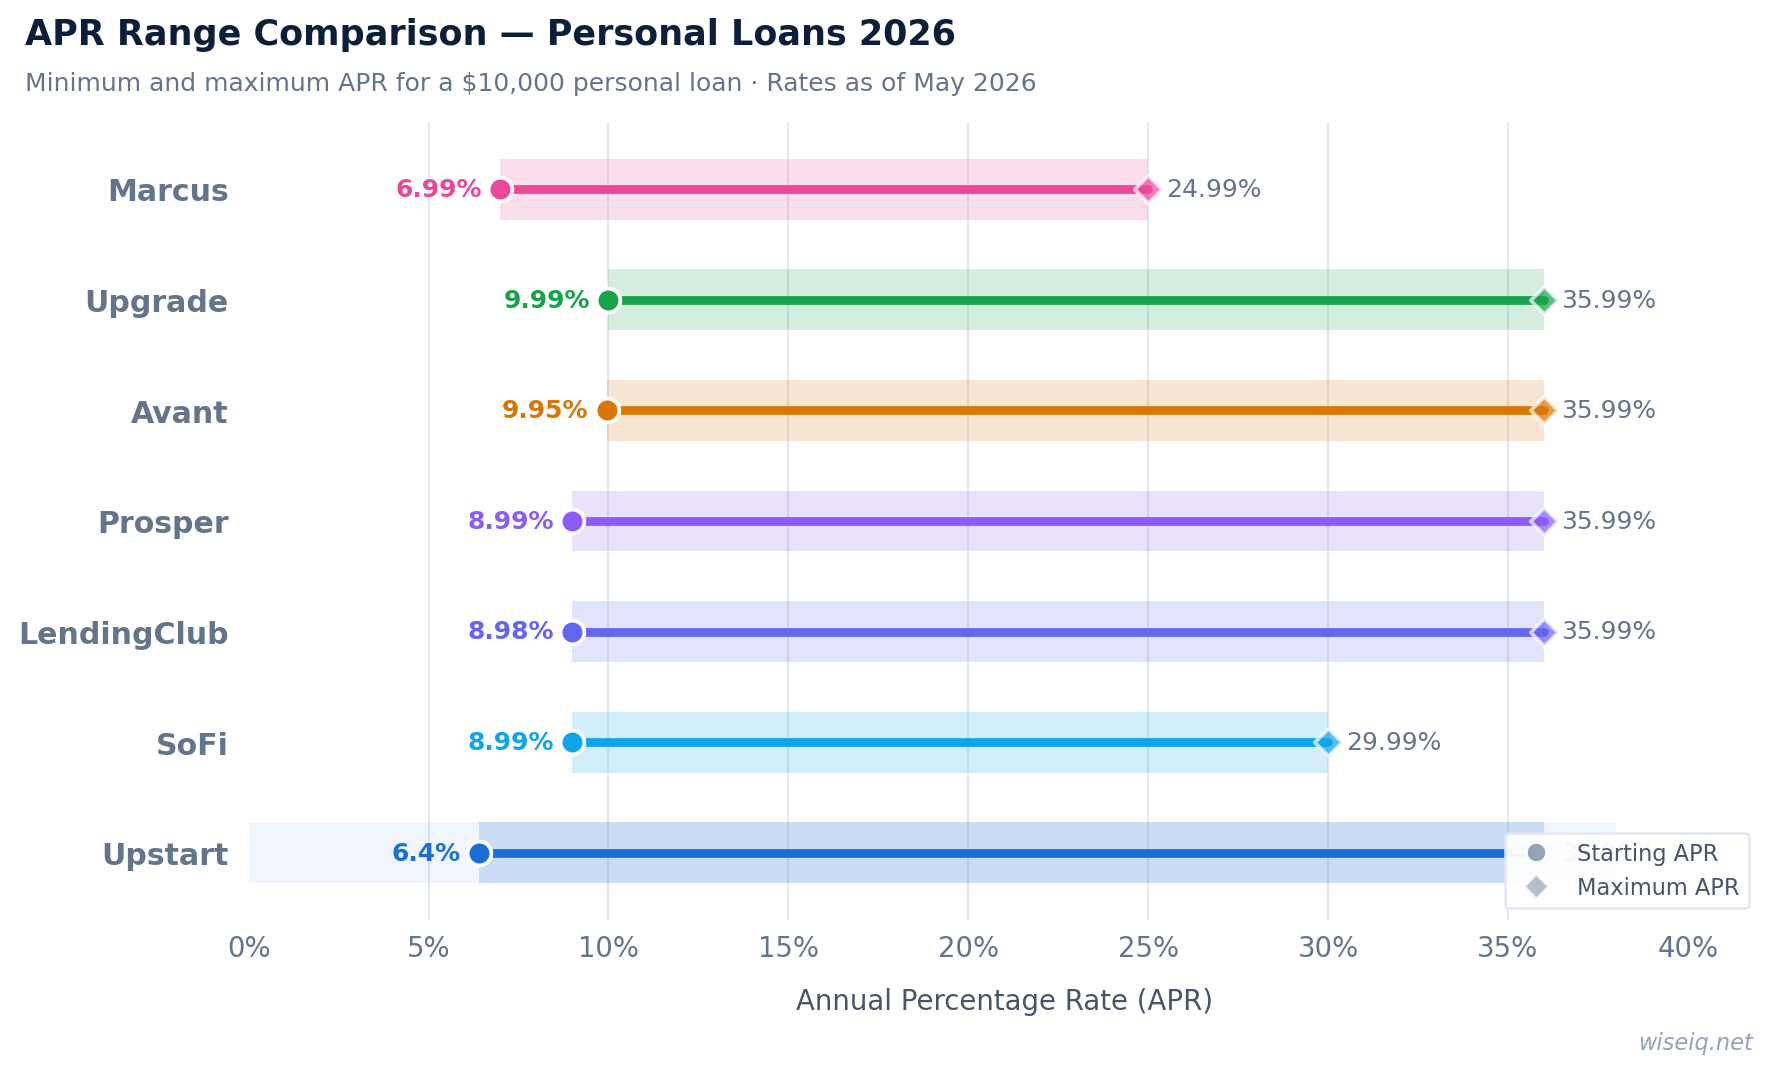
| APR Range | 6.3% – 35.99% | 7.74% – 35.99% |
| Loan Amounts | $1,000 – $75,000 | $1,000 – $50,000 |
| Loan Terms | 3 or 5 years | 2 – 7 years |
| Min. Credit Score | None (AI-based) | 600 |
| Origination Fee | 0% – 12% | 1.85% – 9.99% |
| Time to Fund | 1 business day | 1 business day |
| Prepayment Penalty | None | None |
| Soft Pull for Rate | Yes | Yes |
Getting approved and getting funded are two different steps, and most people who lose the loan lose it in between. Three things that decide it:
- Ask for what your score supports. Under a 660 score, $5,000 to $15,000 gets approved far more often than $25,000 and up. A smaller request usually means a real offer instead of a decline.
- Accept and verify the same day. Offers expire. Have a recent pay stub or bank statement ready to upload, and answer the verification email or call quickly.
- The origination fee comes out of the deposit. It runs 0% to 12%. A $10,000 loan with an 8% fee puts $9,200 in your account, so size the request with the fee in mind.
When to Choose Upstart
Upstart is the better choice if your credit score is below 600, if you need more than $50,000, or if you have a thin credit file. Upstart's AI underwriting considers education and work history, giving it an edge for non-traditional borrowers.
Who Upstart Is Best For
⚠️ Not a fit if: you need a secured loan, have a bankruptcy in the last 12 months, or need more than $50,000.
What Happens When You Click — 3 Steps
- You have a limited credit history or no credit score at all
- You need more than $50,000 (Upstart goes up to $75,000)
- You want funds in 1 business day
- You want to check your rate without a hard credit pull
- Your education or employment history is stronger than your credit score suggests
See who actually approves your score range — and the APR to expect.
When to Choose Upgrade
Upgrade is a strong alternative if you have a credit score of 600 or higher and want direct payment to creditors for debt consolidation. Upgrade also offers a secured loan option backed by your vehicle.
Upstart: Pros & Cons
✅ Pros
- No minimum credit score
- AI-based underwriting (education + work history)
- Loans up to $75,000
- Funds in 1 business day
- Soft pull for rate check
- No prepayment penalty
- Available in all 50 states
⚠️ Cons
- Origination fee up to 12%
- Only 3 or 5 year terms (no 7-year option)
- Rates can be high for lower credit profiles
- No co-signer option
Upgrade: Pros & Cons
✅ Pros
- APR from 7.74%
- Loan amounts up to $50,000
- Origination fee: 1.85% – 9.99%
- Funding: 1 business day
⚠️ Cons
- Requires min. credit score of 600
- Lower max loan than Upstart
- May not accept thin credit profiles
💡 Expert Tip: Check Your Rate Before You Commit
Upstart offers prequalification with a soft credit pull — meaning you can check your rate in minutes without any impact to your credit score. Before applying, review your debt-to-income ratio (DTI): Upstart looks for a DTI below 45–50%. Divide your total monthly debt payments by your gross monthly income to calculate yours. A lower DTI improves your approval odds and typically results in a lower APR.
Frequently Asked Questions
WiseIQ may earn a referral fee from some lenders on this page. This does not influence our editorial ratings or recommendations. Our reviews are independently researched and editorially independent. Updated September 2026.